A Trust-First Homepage Checklist with Compliance Traps to Avoid for Financial Advisors
Financial advisor website design checklist for your homepage: clear headline, proof, credentials, one call to action, and compliance traps to check.
Updated: 10/27/2026 by Cullen Fischel
A referred prospect judges your site before the first call
A physician gets your name from a colleague, opens your website, and decides within seconds whether to book. If your site is outdated or missing, that decision may go against you before you speak. A 2025 study reported that 96% of referred prospects researched an advisor and 72% visited the website. Nielsen Norman Group's eyetracking research found users spend 57% of viewing time above the fold, and a separate study found visual appeal can be judged in about 50 milliseconds. That speed covers visual appeal only. Your first screen still has to give a careful reader something to verify.
Good financial advisor website design puts four things in that first screen:
- Who you serve: a specific client type and problem
- Proof: facts a visitor can check
- Credentials: accurate, visible qualifications
- One call to action: a single next step
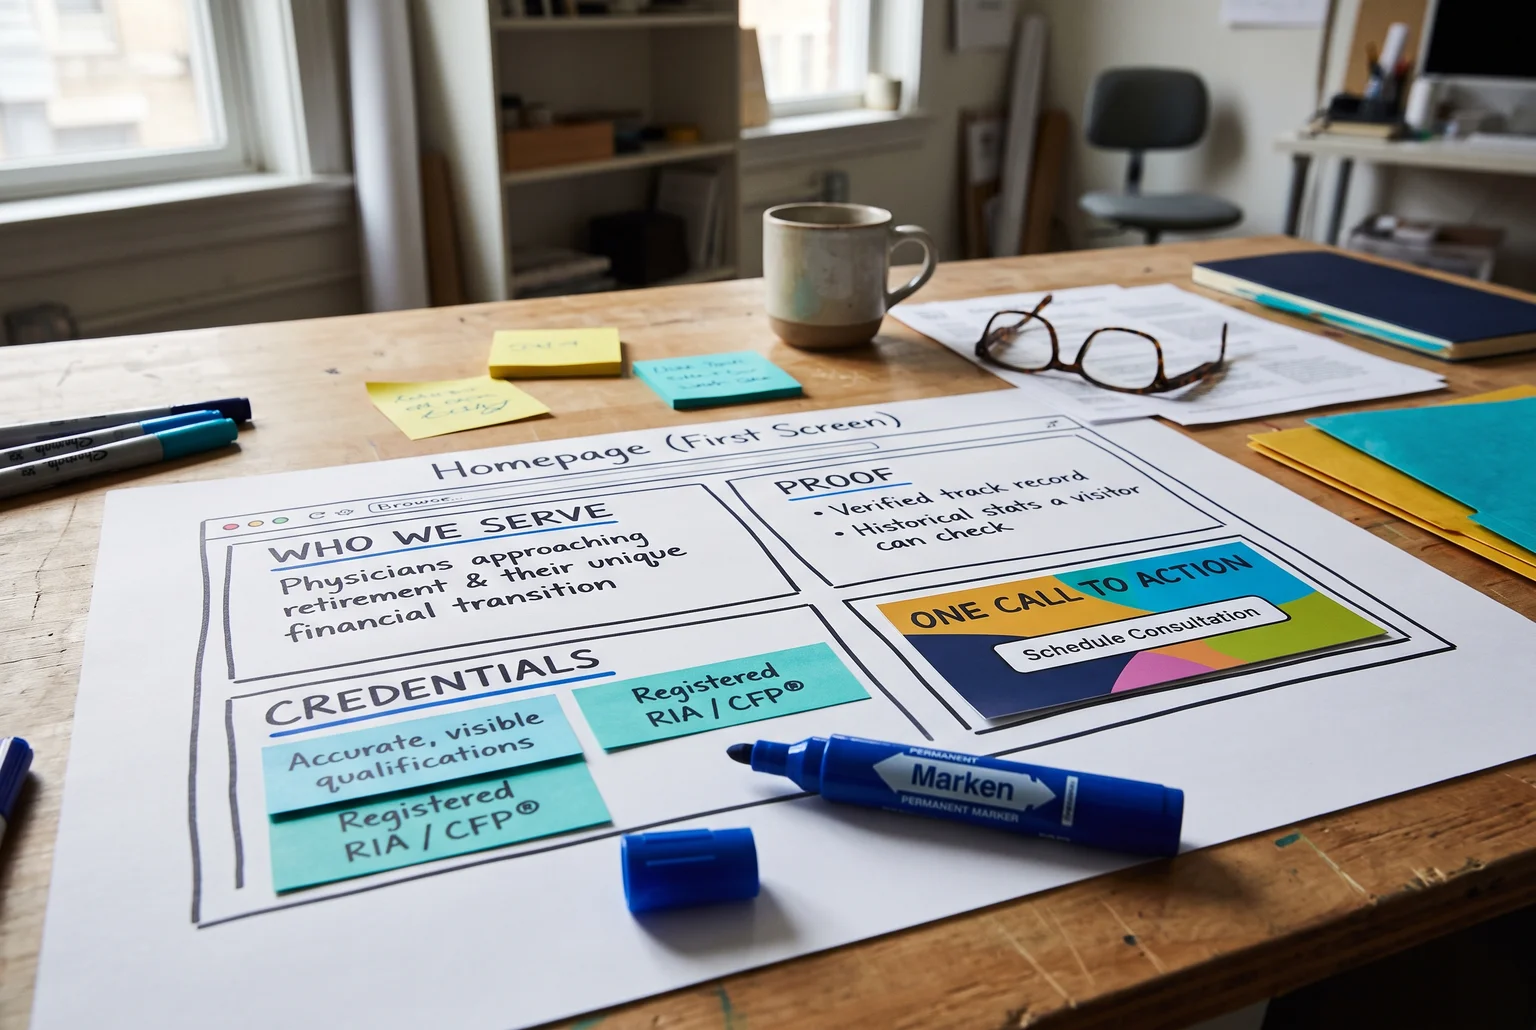
The running example is an independent RIA serving physicians approaching retirement. Each section below pairs a trust element with a compliance trap to check. For a fuller view of the design side, see our guide to professional financial advisor website design.
This is a design and marketing checklist. Nothing here is legal advice, and following it does not ensure compliance. Review your homepage with your compliance professional or counsel.
Which rule governs your homepage: SEC or FINRA
The compliance flags depend on how you are registered. An RIA or investment adviser representative looks to the SEC Marketing Rule. A broker-dealer registered representative looks to FINRA Rule 2210. Dually registered or hybrid advisors may need to consider both.
Quick Definition: The SEC Marketing Rule is Rule 206(4)-1 under the Advisers Act. It replaced the former advertising and cash-solicitation rules.
| RIA (SEC Marketing Rule) | Broker-dealer rep (FINRA Rule 2210) | |
|---|---|---|
| Scope | A homepage that offers advisory services may be an advertisement | Communications with the public, including websites under Notice 17-18 |
| Content standard | No false or misleading statements | Fair and balanced; no promissory or exaggerated claims |
| Testimonials | Permitted with disclosures and oversight; written promoter agreements generally required | Handled through FINRA's rule and notices |
| Performance | Gross figures need net figures with equal prominence | Claims, rankings and awards must be substantiated |
| Approval and records | Retain advertisements and supporting materials | Principal approval, recordkeeping, and a filing requirement for new member firms |
Both regimes bar misleading content. The SEC rule sets specific conditions for testimonials, endorsements, third-party ratings and performance, while FINRA's rule adds principal approval and filing procedures. Confirm which flags apply to your firm with your compliance professional or counsel.
Name your client and the problem in the headline and subhead
Headline
Name the client type and the service. A homepage should make clear where users are, what the organization does, and what they can do there, and generic wording like "wealth management" fails to identify the audience, service, or location. Specific copy also matches the niche and local queries your prospects type.
Subhead
State the problem or outcome you work on, without promising a result. A short tagline is enough.
| Headline | Subhead | |
|---|---|---|
| Weak | Comprehensive wealth management for your future | Personalized solutions for every stage of life |
| Stronger | Retirement income planning for physicians | We help physicians within ten years of retirement plan taxes, practice sale proceeds, and withdrawals. |
The stronger version names the client, the service, and the problem. Niche positioning also separates you from the many firms that describe themselves identically.
Compliance flags
Avoid "best," "guaranteed," and "protect your wealth." Both the SEC Marketing Rule (no unsubstantiated material statements of fact, fair and balanced treatment of risks when benefits are discussed) and FINRA Rule 2210(d)(1)(B) (no exaggerated, promissory, or misleading claims) apply here. FINRA also says fine print cannot cure a claim that is misleading on its face. "Specialist in physician planning" needs a basis such as credentials, experience, or client concentration.
Show proof you can stand behind
Factual proof
Place client types served, years in practice, and media mentions near the headline. "Serving physicians since 2009" works only if the date is accurate. Link a media mention to the actual piece, and send any compensated placement to compliance.
Reviews and ratings
This element carries the most risk.
RIAs. The SEC Marketing Rule allows testimonials and endorsements with clear and prominent disclosure of client status, compensation, and material conflicts. Compensated promoters generally need a written agreement, though compensation of $1,000 or less in 12 months is exempt. Third-party ratings need disclosure of the rating date, review period, provider, and any compensation.
Broker-dealer reps. FINRA Rule 2210(d)(6) requires testimonials about investment advice or performance to state that they may not be representative, and to disclose payments above $100. Under Regulatory Notice 17-18, a firm that pays for or helps prepare third-party content is "entangled" with it. Hybrid advisors should have compliance check both rulebooks.
Traps and lower-risk alternatives
Review the provider's methodology, rating period, compensation, and disclosure wording before embedding a Google review feed, star rating, or "Top Advisor" badge. Showing only favorable reviews can mislead, and the SEC prohibits cherry-picking.
A process description ("three meetings, then a written plan") and a client-fit statement ("a fit for physicians within ten years of retirement; not a fit for investors seeking stock picks") build trust without a testimonial. Compliance should still review the wording.
Show credentials and disclosure links where visitors expect them
Credentials and a real headshot
Put your name, a recent photo, and one or two credentials in the header or just under the headline. List only designations you currently hold, and say what you are registered as.
The CFP Board says to capitalize the marks, omit periods, include the ® symbol, and attach them to the certified individual, not the firm. It also bars using the marks in a domain name or email address and altering the logo.
Common Mistake: Writing "CFP Wealth Partners" in a logo or URL, or listing a designation that has lapsed or is still in progress.
The SEC describes an adviser's fiduciary duty as a duty of care and a duty of loyalty. Apply "fiduciary" to your advisory services only. The SEC has also charged advisers over hedge clauses implying clients waived fiduciary duties.
Disclosure links
SEC-registered advisers and broker-dealers serving retail investors generally prepare a Form CRS. A firm with a website must post it prominently and make it readily accessible, so a footer link alone may not meet that standard. Ask compliance. Link Form ADV Part 2A and registration disclosures nearby.
Broker-dealer reps must also include the BrokerCheck reference and link required by FINRA Rule 2210, and FINRA generally does not consider a footer link "readily apparent".
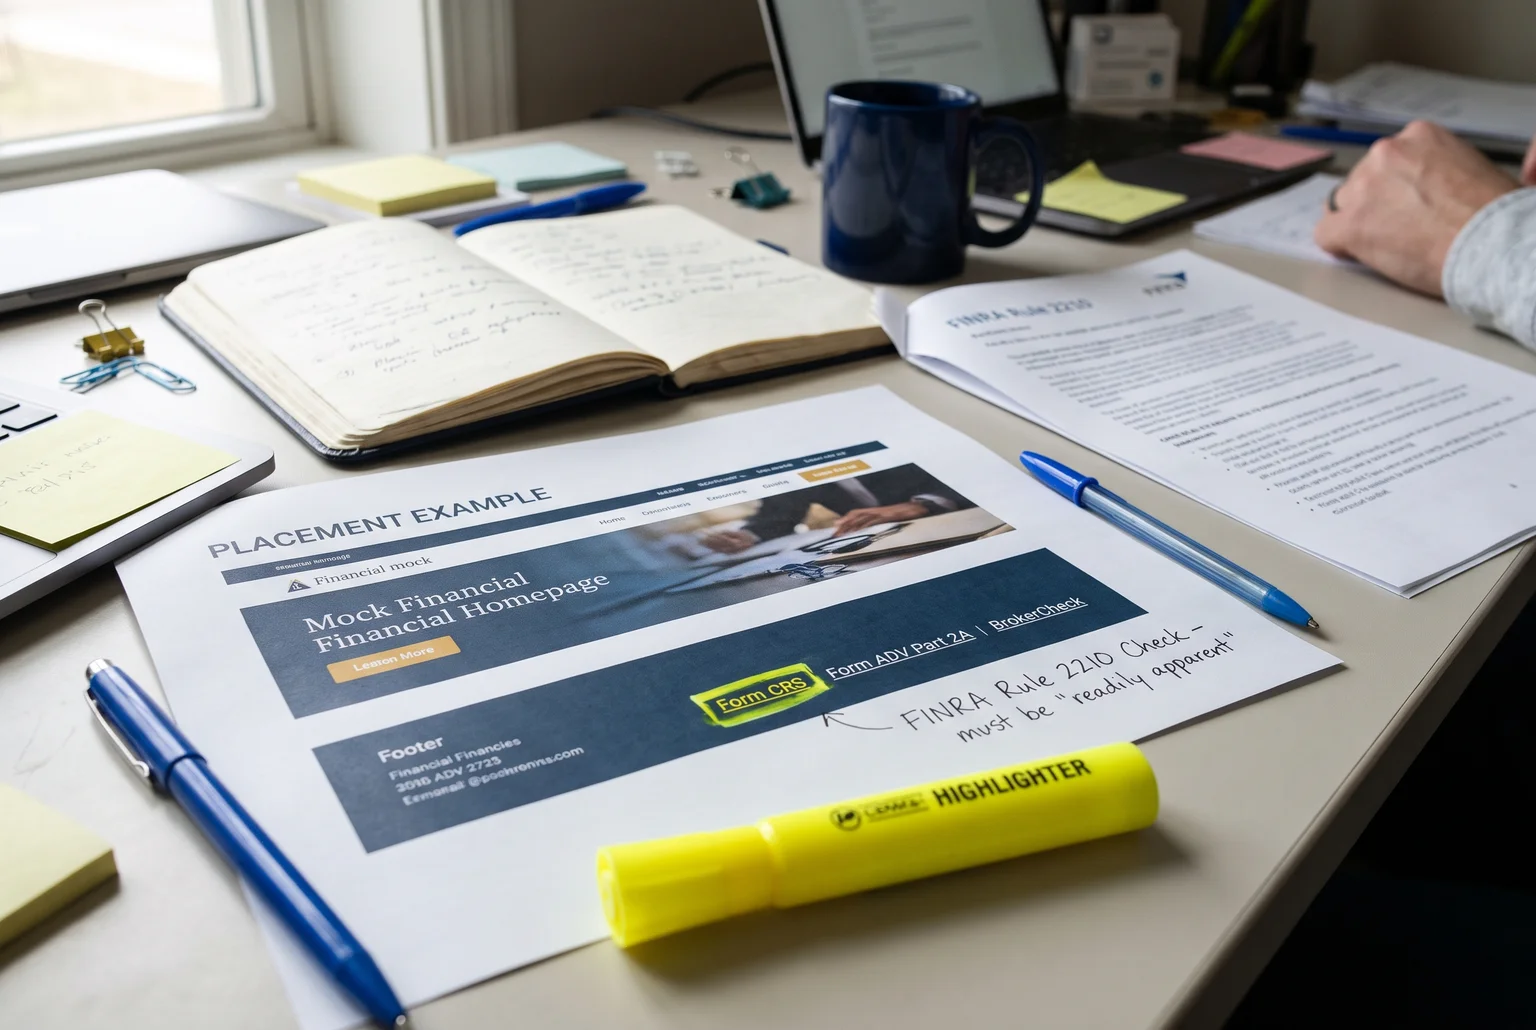
Listing these links does not satisfy any disclosure obligation by itself.
Pick one booking action and keep contact details visible
One primary call to action
Use a single button, such as "Book an introductory call," that links straight to a short scheduling flow. Put a phone number and professional email beside it, plus a "Client login" link in the header for existing clients, so they never compete with prospects for the main button.
An analysis of 18,639 landing pages reported 13.5% average conversion with one link versus 10.5% with five or more. That is aggregated page-level data, so it does not show a single button will lift your homepage. Other testing reports multiple CTAs lifting engagement. Test your own page, and expect that only about 12% of A/B tests produce a significant gain.
Lead capture after the first screen
Place a lead magnet or email signup below the main action. Keep form labels visible while people type, as Baymard advises, and explain data use beside the form with a privacy notice link.
Compliance flags
- Skip urgency or implied-results wording ("limited spots," "grow your wealth").
- Separate appointment emails from marketing subscriptions.
- Archive page versions, lead-magnet disclosures, consent language and automated emails. The SEC charged an adviser in September 2025 for failing to preserve website advertisements.
- Advisers generally keep communications five years; broker-dealers, three. Confirm with compliance.
Design, speed and SEO basics that support trust
Visitors read a slow, cluttered or insecure page as a careless firm. Keep navigation to five or six labels, use real photos of you and your office, and apply one logo and color set everywhere. Pass Core Web Vitals, serve HTTPS, meet 4.5:1 text contrast, and match your name and contact details to your Google Business Profile.
Compliance traps include stock photos implying clients, embedded third-party articles that may be treated as adopted, and "best of" badges without ratings disclosures. The SEC's 2024 sweep cited advisers for missing ones.
Advisor-specific templates usually include approval and archiving workflows. General builders and custom design offer more freedom but leave backups and updates to you.
What to budget for an advisor website, and what to ask a provider
Published prices vary and change, and they are benchmarks rather than quotes. Template builders run about $16 to $50 a month, advisor-specific platforms roughly $100 to $400 or more, and custom agency builds several thousand dollars plus possible retainers. One agency lists flat tiers from $2,250 to $5,000. Copywriting, photography, integrations, compliance review and maintenance often cost extra, and they drive the final price more than the platform does.
Low-cost builders give you control but put time and compliance responsibility on you. Specialized providers reduce that work but add recurring fees and platform dependence.
Questions to ask any provider:
- Which financial-services firms have you built for, and what was their compliance workflow?
- Who writes and approves the copy, and how are testimonials and performance claims handled?
- Are changes archived, and can records be exported for an examination?
- What is excluded from the quote?
Compare several providers against these answers, including advisor-focused design agencies.
Trust-first homepage checklist
This checklist is not legal advice and does not guarantee compliance. Have your compliance professional review the finished page, and confirm whether your firm follows the SEC Marketing Rule, FINRA Rule 2210, or both.
First screen
- Headline names your client type and service (for example, retirement income planning for physicians).
- Subhead states the problem you work on without promising a result.
- No "best," "guaranteed," or "protect your wealth" wording, and any "specialist" claim has a documented basis.
- One primary button, such as "Book an introductory call," with phone and email beside it.
- Client login link sits in the header, away from the main button.
Proof
- Years in practice, client types served, and media mentions are accurate and linked to the original source.
- Testimonials and endorsements carry the required disclosures and oversight for RIAs, or follow FINRA Rule 2210 for broker-dealer reps.
- Review feeds, star ratings, and "Top Advisor" badges have been checked for methodology, compensation, and disclosure wording.
- Reviews are not cherry-picked.
- Process description and client-fit statement are in place as lower-risk proof.
Credentials and disclosures
- Real headshot, name, and one or two designations you currently hold.
- CFP marks are used correctly and never appear in a firm name, domain, or email address.
- "Fiduciary" applies only to your advisory services, and no hedge clause implies clients waived rights.
- Form CRS is posted prominently where required, not only in the footer.
- Form ADV Part 2A and registration disclosures are linked nearby.
- Broker-dealer reps include the BrokerCheck reference and link.
Lead capture and records
- Signup sits below the main action, with visible form labels and a privacy notice link.
- No urgency or implied-results wording in lead magnets or emails.
- Appointment emails are separate from marketing subscriptions.
- Page versions, lead-magnet disclosures, consent language, and automated emails are archived for the retention period compliance specifies.
Design and technical
- Navigation has five or six labels.
- Photos are real, with no stock images implying clients.
- Pages pass Core Web Vitals, use HTTPS, and meet 4.5:1 text contrast.
- Name and contact details match your Google Business Profile.
- Embedded third-party articles are reviewed for adoption or entanglement.
Ongoing review
- A blog that promotes your services may be an advertisement, so route posts through your review process.
- Review compliance policies at least annually, and recheck the homepage each time you change it.
Walk your homepage through this list with your compliance professional, or request a homepage review.
About Cullen Fischel
Cullen Fischel is the lead designer at Pro Financial Design. So, if you’ve ever worked with us, you’ve worked with Cullen on strategy, design, and content creation for your project. Cullen’s got years of experience developing websites, brands, logos, lead magnets, digital marketing strategies, and social and email content for his clients. If you have any questions for him, just send us a message!
Want more financial advisor marketing tips and guides? Check out: